
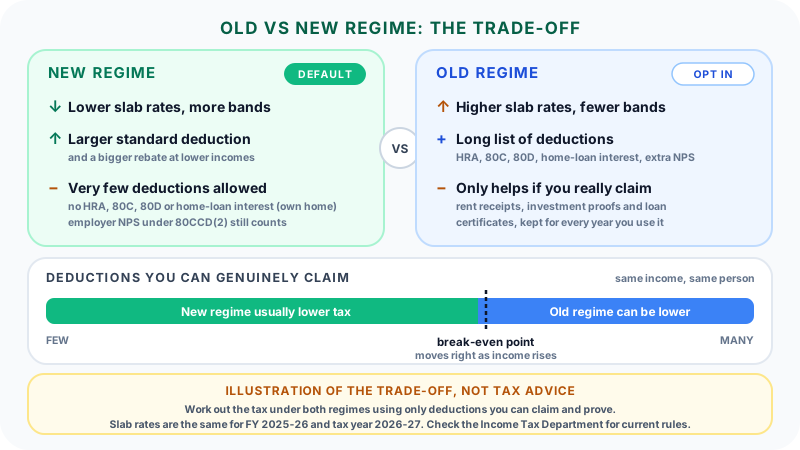
Every year, salaried employees in India are asked the same question by their payroll team: old regime or new regime? The new regime has lower slab rates. The old regime lets you subtract HRA, Section 80C investments, health insurance, and home-loan interest before tax is worked out. Which one costs less is not a matter of opinion. It is arithmetic, and the answer depends on two things: how much you earn and how much you can genuinely deduct.
This guide explains both regimes in plain English, gives the current slabs with the tax year clearly labelled, shows which deductions each regime allows, and works through salary examples. To run your own numbers, the India Income Tax Calculator applies the slabs, standard deduction, rebate, and cess for you.
Important: This is general information, not tax advice. It covers resident individuals with salary income. Capital gains, business income, non-residents, and very high incomes have extra rules. Check the Income Tax Department's official pages or ask a qualified chartered accountant before making a decision.
Which tax year this article covers
Two tax years matter in September 2026, and the good news is that the rates are the same for both.
| Period | Old name | Law | Status in September 2026 |
|---|---|---|---|
| 1 April 2025 to 31 March 2026 | FY 2025-26 (AY 2026-27) | Income-tax Act, 1961 | Returns filed in 2026 |
| 1 April 2026 to 31 March 2027 | Tax year 2026-27 (what used to be FY 2026-27, AY 2027-28) | Income-tax Act, 2025 | Current year; TDS and advance tax |
The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026. It replaces the separate ideas of "previous year" and "assessment year" with a single tax year that matches the financial year. The Income Tax Department states that the new Act "does not impose any new tax", and the Finance Bill 2026 memorandum confirms that the individual rates for tax year 2026-27 are the same as those for FY 2025-26.
Returns for FY 2025-26 (AY 2026-27) are still filed under the old Act and its forms. The new Act also renumbers the law. For example, the new regime moves from Section 115BAC to Section 202. This article uses the familiar old section names, such as 80C, 80D and 87A, because payslips, investment declarations and FY 2025-26 returns still use them.
The two regimes in one paragraph each
The new regime has more slabs and lower rates, a larger standard deduction, and a rebate that removes all tax on taxable income up to ₹12 lakh. In exchange, most deductions and exemptions are not allowed. It is the default: if you do nothing, your tax is worked out under the new regime.
The old regime has fewer slabs and higher rates, but it allows the long list of deductions and exemptions many salaried people have used for years: HRA, LTA, Section 80C, Section 80D, home-loan interest on a self-occupied house, extra NPS contributions under Section 80CCD(1B), and others. You have to choose it.
Current tax slabs
These slabs apply to both FY 2025-26 (AY 2026-27) and tax year 2026-27. They are applied to taxable income, meaning income after the deductions each regime allows.
New regime (default)
The same slabs apply at every age.
| Taxable income | Rate |
|---|---|
| Up to ₹4,00,000 | Nil |
| ₹4,00,001 to ₹8,00,000 | 5% |
| ₹8,00,001 to ₹12,00,000 | 10% |
| ₹12,00,001 to ₹16,00,000 | 15% |
| ₹16,00,001 to ₹20,00,000 | 20% |
| ₹20,00,001 to ₹24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Old regime (optional)
The tax-free amount depends on age.
| Taxable income | Below 60 | Senior (60 to 79) | Super senior (80+) |
|---|---|---|---|
| Up to ₹2,50,000 | Nil | Nil | Nil |
| ₹2,50,001 to ₹3,00,000 | 5% | Nil | Nil |
| ₹3,00,001 to ₹5,00,000 | 5% | 5% | Nil |
| ₹5,00,001 to ₹10,00,000 | 20% | 20% | 20% |
| Above ₹10,00,000 | 30% | 30% | 30% |
Slabs are progressive. Each rate applies only to the part of income inside that band, not to your whole income. Under the new regime, someone with ₹10 lakh of taxable income pays 5% on ₹4 lakh and 10% on ₹2 lakh, which is ₹40,000 before the rebate, not 10% of ₹10 lakh.
Standard deduction, rebate, cess and surcharge
Four more pieces sit around the slabs.
| Item | New regime | Old regime |
|---|---|---|
| Standard deduction (salary or pension) | ₹75,000 | ₹50,000 |
| Section 87A rebate (resident individuals) | Up to ₹60,000 if taxable income is ₹12,00,000 or less | Up to ₹12,500 if taxable income is ₹5,00,000 or less |
| Health and education cess | 4% of tax plus surcharge | 4% of tax plus surcharge |
| Surcharge | 10% above ₹50 lakh, 15% above ₹1 crore, 25% above ₹2 crore (capped at 25%) | Same bands, plus 37% above ₹5 crore |
The rebate is why people say income up to ₹12 lakh is tax-free under the new regime. The slab tax on exactly ₹12 lakh of taxable income is ₹60,000, and the rebate cancels it. Add the ₹75,000 standard deduction and a salaried person can earn up to ₹12.75 lakh of salary and pay no income tax. The government's own announcement makes one caveat: this applies to normal income, not special-rate income such as capital gains.
Marginal relief stops a cliff just above ₹12 lakh. Under the new regime, if taxable income goes slightly over ₹12 lakh, the tax you pay cannot be more than the amount by which your income exceeds ₹12 lakh. For example, at ₹12,25,000 of taxable income the slab tax is ₹63,750, but marginal relief limits it to ₹25,000 (about ₹26,000 with cess). Surcharges above ₹50 lakh have a similar relief rule.
Deductions: what each regime allows
This table is where the real comparison happens.
| Deduction or exemption | Old regime | New regime |
|---|---|---|
| Standard deduction on salary or pension | ₹50,000 | ₹75,000 |
| HRA exemption | Yes, if you pay rent and meet the conditions | No |
| LTA exemption | Yes, within the rules | No |
| Section 80C (EPF employee share, PPF, ELSS, life insurance premium, principal on a home loan, children's tuition fees and others) | Up to ₹1,50,000 in total | No |
| Section 80CCD(1B): your own extra NPS contribution | Up to ₹50,000, on top of 80C | No |
| Section 80CCD(2): employer's NPS contribution | Up to 10% of salary (14% for government employers) | Up to 14% of salary |
| Section 80D: health insurance | Up to ₹25,000 for self and family and up to ₹25,000 for parents (₹50,000 each where the insured person is a senior citizen) | No |
| Section 24(b): home-loan interest, self-occupied house | Up to ₹2,00,000 | No |
| Section 24(b): home-loan interest, let-out house | Yes | Yes, but the loss cannot be set off against salary or carried forward |
| Section 80E (education loan interest), 80G (donations), 80TTA/80TTB (deposit interest) | Yes, within limits | No |
| Family pension deduction | Yes | Yes (₹25,000 limit under the new regime) |
The new regime is not quite "no deductions", but for most salaried people the only items that matter are the ₹75,000 standard deduction and, if your employer offers it, employer NPS under Section 80CCD(2).
Some exemptions don't depend on the regime because they apply to money you receive at retirement or on leaving a job, not to your annual deductions. Examples include gratuity up to the statutory limit and EPF withdrawals that meet the conditions. The Gratuity Calculator and EPF Calculator help with those.
A note on HRA
HRA is often the largest old-regime exemption for people who rent. The exempt amount is the lowest of:
- the HRA you actually receive,
- rent paid minus 10% of salary (basic plus DA), and
- 50% of salary in the specified metro cities, or 40% elsewhere.
For FY 2025-26, the 50% cities are Mumbai, Delhi, Kolkata and Chennai. Several reports say that the Income-tax Rules, 2026 add Bengaluru, Hyderabad, Pune and Ahmedabad to the 50% list from tax year 2026-27, but check the notified rules before relying on this. If you pay rent to a family member, you need a genuine arrangement: real payments, a rent agreement, and the landlord declaring the rent as income. If the arrangement is informal, the exemption can be disallowed.
Worked examples
All examples below assume a resident individual under 60 with only salary income. Tax figures include the rebate, marginal relief where it applies, and 4% cess. Because the rates are unchanged, the results are the same for FY 2025-26 and tax year 2026-27. Deductions are listed in addition to the standard deduction.
Example 1: ₹12.75 lakh salary, no deductions
| Old regime | New regime | |
|---|---|---|
| Salary | ₹12,75,000 | ₹12,75,000 |
| Standard deduction | ₹50,000 | ₹75,000 |
| Taxable income | ₹12,25,000 | ₹12,00,000 |
| Tax after rebate, with cess | ₹1,87,200 | Nil |
With no deductions to claim, the old regime charges about ₹1.87 lakh more at this salary. To get down to zero tax under the old regime, taxable income would have to fall to ₹5 lakh, which means finding ₹7.25 lakh of deductions.
Example 2: Riya, ₹14 lakh, a typical "tax-planned" salary
Riya rents a flat and claims ₹1,80,000 of HRA exemption. She uses the full ₹1,50,000 under Section 80C, mostly through EPF, and pays ₹25,000 of health insurance under Section 80D. That is ₹3,55,000 of deductions on top of the standard deduction.
| Old regime | New regime | |
|---|---|---|
| Taxable income | ₹9,95,000 | ₹13,25,000 |
| Tax with cess | ₹1,15,960 | ₹81,900 |
Many people expect the old regime to win here. Under the current slabs it doesn't: the new regime is about ₹34,000 cheaper. Deductions of ₹3.55 lakh are real, but at ₹14 lakh they aren't big enough to beat the new regime's lower rates and larger rebate.
Example 3: ₹18 lakh salary, four levels of deductions
The same salary gives a new-regime tax of ₹1,50,800 (taxable income ₹17,25,000) whatever the person invests. The old-regime figure moves with deductions:
| Deductions claimed (besides standard deduction) | Old-regime taxable income | Old-regime tax with cess | Lower tax |
|---|---|---|---|
| ₹1,50,000 (80C only) | ₹16,00,000 | ₹3,04,200 | New, by ₹1,53,400 |
| ₹3,55,000 (HRA ₹1.8L, 80C, 80D ₹25k) | ₹13,95,000 | ₹2,40,240 | New, by ₹89,440 |
| ₹6,40,000 (HRA ₹2.4L, 80C, 80D ₹50k, home-loan interest ₹2L) | ₹11,10,000 | ₹1,51,320 | Almost equal (new by ₹520) |
| ₹6,90,000 (the above plus ₹50,000 NPS under 80CCD(1B)) | ₹10,60,000 | ₹1,35,720 | Old, by ₹15,080 |
At ₹18 lakh, the old regime only comes out ahead once deductions pass roughly ₹6.4 lakh. In practice that usually means a self-occupied home loan, a substantial HRA claim, full 80C, 80D, and extra NPS all at once.
Break-even deductions at different salaries
Using the same assumptions, this is roughly how much you would need to deduct under the old regime, on top of the standard deduction, before it matches the new regime:
| Gross salary | Deductions needed for the old regime to match |
|---|---|
| ₹10,00,000 | ₹4,50,000 (both regimes then reach nil tax) |
| ₹12,75,000 | ₹7,25,000 (both regimes then reach nil tax) |
| ₹15,00,000 | about ₹5,44,000 |
| ₹18,00,000 | about ₹6,42,000 |
| ₹20,00,000 | about ₹7,08,000 |
| ₹25,00,000 to ₹50,00,000 | about ₹8,00,000 |
These are illustrations, not thresholds written in law. Surcharge above ₹50 lakh, employer NPS, age, and other income all move the numbers. What the table shows is the pattern: the old regime needs a lot of deductions to win, and even more once your salary is high enough for the new regime's lower rates to save you a lot.
Why neither regime is "better"
Nothing in the tax rules makes one regime better for everyone. The lower tax comes from the same calculation every time:
- Work out taxable income under each regime, using only deductions you can actually claim and prove.
- Apply that regime's slabs.
- Apply the rebate (and marginal relief if you are just above ₹12 lakh under the new regime).
- Add surcharge if it applies, then 4% cess.
A few patterns show up often:
- Up to about ₹12.75 lakh of salary, the new regime usually means zero tax, and the old regime rarely matches it.
- Renters with a large HRA claim and a self-occupied home loan are the group most likely to find the old regime cheaper, and usually only at higher salaries.
- People who invest in 80C products only to save tax should compare carefully. If the new regime already costs less, those products need to be worth buying for their own sake.
Also count your time. The old regime involves more paperwork, such as rent receipts, investment proofs and loan certificates. That doesn't change the tax, but it is a fair thing to weigh when the difference is small.
Choosing and switching
For FY 2025-26 returns, the Income Tax Department's guidance is:
- The new regime applies automatically unless you opt out.
- If you have no business or professional income, you can choose either regime each year in your return, filed by the due date, and switch again the following year.
- If you have business or professional income, you opt out by filing Form 10-IEA by the due date. After opting out, you can switch back to the new regime only once, and after that you cannot choose the old regime again.
What you tell your employer at the start of the year only decides how much TDS is taken from your salary. You make the final choice in your return. If you told payroll one regime and file under the other, the difference is settled as a refund or extra tax when you file.
For tax year 2026-27, the new regime continues as the default under Section 202 of the Income-tax Act, 2025. The forms and rules have been rewritten for the new Act, so check the current official guidance for how to opt out in that year.
Comparing your own figures with the calculator
The India Income Tax Calculator works out one regime at a time, so do the comparison in two passes:
- New regime: enter your gross annual salary, choose your age group, keep the salaried standard deduction switched on, and leave eligible deductions at zero (or enter only employer NPS under 80CCD(2), if you have it).
- Old regime: switch the regime, keep the same salary and age, and enter the total of the deductions you can actually claim: HRA exemption, 80C, 80CCD(1B), 80D, home-loan interest and so on.
- Compare the two tax figures. The difference is roughly what the choice is worth to you this year.
The calculator applies the slabs, the standard deduction, the 87A rebate and 4% cess using the FY 2025-26 (AY 2026-27) rates, which are the same rates that apply in tax year 2026-27. It does not model surcharge above ₹50 lakh, marginal relief just above ₹12 lakh, capital gains, or other special-rate income. If your taxable income is just over ₹12 lakh under the new regime, your actual tax may be lower than the calculator shows.
Before you compare, the Salary Calculator can help you turn a CTC figure into gross salary.
Common mistakes
Comparing slab rates instead of tax bills. A 30% slab under the old regime can still produce a lower bill if enough income is deducted. Always compare the final figures.
Counting deductions you won't actually claim. An 80C limit you haven't used, or HRA without real rent payments, doesn't reduce your tax.
Forgetting that EPF already fills 80C. Your employee EPF contribution counts towards the ₹1,50,000 limit. Many people are closer to the cap than they think, so extra 80C investments may save nothing more.
Using an old year's slabs. Before FY 2025-26, the new regime's nil band ended at ₹3 lakh and its rebate threshold was ₹7 lakh. Advice written before February 2025 can give the wrong answer.
Forgetting cess. The 4% health and education cess applies under both regimes, on tax plus any surcharge.
Assuming the ₹12 lakh rebate covers capital gains. Special-rate income such as capital gains is treated differently, so the "no tax up to ₹12 lakh" rule may not apply in full.
FAQs
Which tax regime is the default in India? The new regime. It has been the default for individuals since FY 2023-24 and remains so under the Income-tax Act, 2025. You have to opt out actively to use the old regime.
Is the new regime always better for salaried employees? No. It gives lower tax for most people with modest deductions, and for almost everyone with salary up to ₹12.75 lakh. People with large, genuine deductions, typically HRA plus a self-occupied home loan plus full 80C, 80D and NPS, can still pay less under the old regime. Compare both before deciding.
Does the new regime allow any deductions at all? A few. The main ones for salaried people are the ₹75,000 standard deduction and employer NPS contributions under Section 80CCD(2), up to 14% of salary. Family pension deduction and interest on a let-out property are also allowed. HRA, 80C, 80D, 80CCD(1B) and home-loan interest on a self-occupied house are not.
Is income up to ₹12 lakh really tax-free? Under the new regime, the Section 87A rebate removes the tax on taxable income up to ₹12 lakh for resident individuals. With the ₹75,000 standard deduction, a salary of up to ₹12.75 lakh can be tax-free. Special-rate income such as capital gains is treated separately.
Can I switch between old and new regimes every year? If you have no business or professional income, yes: you choose in your return each year. If you do have business or professional income, you opt out through Form 10-IEA, and you can switch back to the new regime only once.
Did the Income-tax Act, 2025 change the tax slabs? No. The new Act took effect on 1 April 2026 and changed the structure and section numbers of the law, but the Income Tax Department says it imposes no new tax, and the individual rates for tax year 2026-27 are the same as for FY 2025-26.
How does my EPF contribution interact with the tax regime? Under the old regime, your employee EPF contribution counts towards the ₹1,50,000 Section 80C limit. Under the new regime it doesn't reduce taxable income. EPF withdrawals that meet the conditions are exempt under either regime.
Related guides
- EPF Calculator India: How Your Provident Fund Grows Over Time
- Gratuity Calculator India: Eligibility, Formula, and Real Salary Examples
- Stamp Duty and Registration Charges in India
Sources
- Income Tax Department: Salaried Individuals for AY 2026-27 (slabs, 87A rebate, deduction limits under each regime)
- Income Tax Department: Tax rates (slabs, surcharge and cess, AY 2025-26 and AY 2026-27)
- Income Tax Department: FAQs on New Tax vs Old Tax Regime (default regime, opting out, Form 10-IEA)
- Income Tax Department: Objective and scope of the new Act (Income-tax Act, 2025, tax year, Section 202)
- Ministry of Finance: Memorandum explaining the Finance Bill, 2026 (rates for tax year 2026-27)
- Press Information Bureau: No income tax on annual income up to ₹12 lakh under new tax regime (Budget 2025-26)
- Press Information Bureau: Highlights of the Union Budget 2024-25 (standard deduction, family pension, employer NPS)
This article is educational. India's income tax rules change with each Finance Act, and individual situations vary widely. HRA, NPS, capital gains, surcharge and other income can all change the result. The Income Tax Department is the authoritative source. For decisions, consult a qualified chartered accountant or tax adviser.