
Return on investment, or ROI, answers one question: for every dollar you put in, how much profit came back? It is the most widely used measure of whether a financial decision worked, from buying shares to replacing a piece of equipment to running an ad campaign.
It is also easy to misuse. The basic formula says nothing about how long the money was tied up, how much risk was taken to earn it, or which costs were quietly left out. Two investments with the same ROI can be very different decisions. This guide shows how to calculate ROI properly, and how to read the number once you have it.
Key Takeaways
- ROI = Net profit ÷ Total cost × 100. Net profit is everything you received minus everything you spent.
- A gain is not the same as net profit. A price rise or a sale value ignores fees, running costs and income along the way. Use the full picture on both sides of the division.
- Simple ROI ignores time. 30% over one year and 30% over ten years look identical until you annualize.
- Annualized ROI = (1 + ROI)^(1 ÷ years) − 1. It turns a total return into an equivalent yearly rate so different holding periods can be compared.
- ROI ignores risk. A single realized return does not show how wide the range of possible outcomes was.
- Omitted costs inflate ROI. Most overstated ROI figures come from a denominator that is too small.
The ROI Formula
ROI = (Net Profit ÷ Total Cost) × 100
where:
Net Profit = Total Money Received − Total Money Spent
A $10,000 investment that eventually returns $13,500 in total, with no other costs, has:
ROI = (13,500 − 10,000) ÷ 10,000 × 100 = 35%
A positive ROI means the investment returned more than it cost. A negative ROI means it lost money: −20% means a fifth of the money spent was lost. The lowest possible ROI on an investment you cannot lose more than is −100%.
The formula is the same whether the "investment" is a share purchase, a rental property, a marketing budget or a new machine. What changes from case to case is how carefully the two inputs are defined.
Gain vs Net Profit: The Distinction That Changes the Answer
People often say "gain" when they mean one of two narrower things:
- The price gain: what you sold for minus what you paid.
- The gross proceeds: the total money that came back.
Neither is net profit. Net profit subtracts every cost connected to the investment and adds every stream of income it produced. Using a gain in place of net profit is the most common way an ROI figure ends up wrong while still looking reasonable.
Worked example: one investment, three different "returns"
You buy 100 shares at $50 each and pay a $10 commission. Over three years you receive $400 in dividends. You then sell at $62 per share and pay another $10 commission.
| What is being measured | Calculation | Result |
|---|---|---|
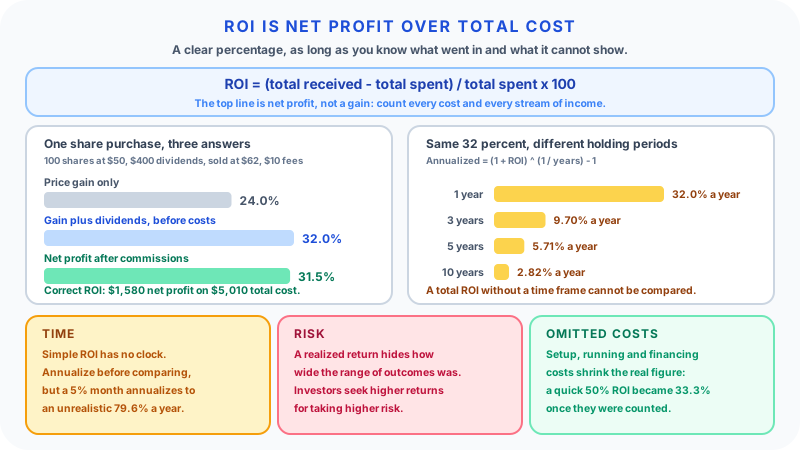
| Price gain only | ($6,200 − $5,000) ÷ $5,000 | 24.0% |
| Price gain plus dividends, before costs | ($6,200 + $400 − $5,000) ÷ $5,000 | 32.0% |
| Net profit ROI | ($6,190 + $400 − $5,010) ÷ $5,010 | 31.5% |
The net profit version uses the money actually received after the selling commission ($6,190), the dividends ($400), and the full cost including the buying commission ($5,010). Net profit is $1,580.
Here the difference between 32.0% and 31.5% is small, because the commissions are small. The gap between 24% and 31.5% is large, because leaving out the dividends understates the return. The lesson runs both ways: an incomplete numerator or an incomplete denominator both give the wrong answer.
All three figures are before tax. If gains or dividends are taxed, the ROI you keep is lower, and the size of the difference depends on your circumstances and where you live.
The rule: the numerator and the denominator must describe the same boundary. If a cost belongs to the investment, it goes in the denominator. If income came from the investment, it belongs in the net profit.
Why ROI Ignores Time, and How Annualizing Helps
The 31.5% above took three years to earn. Simple ROI does not say that, and it matters enormously.
To compare returns over different periods, convert the total into an annualized rate:
Annualized ROI = (1 + Total ROI)^(1 ÷ years) − 1
Using the decimal form of ROI, a 32% return over different periods works out as follows:
| Total ROI | Holding period | Annualized ROI |
|---|---|---|
| 32% | 1 year | 32.0% per year |
| 32% | 3 years | 9.70% per year |
| 32% | 5 years | 5.71% per year |
| 32% | 10 years | 2.82% per year |
Same total return, very different investments.
Worked example: which did better?
- Investment A returned 40% over 4 years.
- Investment B returned 18% over 1 year.
On simple ROI, A looks better. Annualized:
- A: 1.40^(1 ÷ 4) − 1 = 8.78% per year
- B: 1.18^(1 ÷ 1) − 1 = 18.0% per year
B earned its return far faster. Whether B was the better choice still depends on risk, which ROI does not capture, and on whether the money could have been reinvested at a similar rate afterwards.
What annualizing does not do
Annualized ROI is the constant yearly rate that would turn the starting value into the ending value. It is a useful comparison figure, with limits:
- It smooths the path. An investment that fell 30% and then recovered shows the same annualized figure as one that rose steadily.
- It exaggerates very short periods. A 5% return in one month annualizes to 1.05^12 − 1 = 79.6% per year, a rate almost nothing sustains.
- It assumes one payment in and one value out. If money was added or withdrawn along the way, as with regular contributions or rental income, a single start-and-end calculation misstates the return. Internal rate of return (IRR) is the tool built for multiple cash flows at different dates.
The same formula is often called compound annual growth rate (CAGR), and you can run it directly with the CAGR Calculator.
ROI Ignores Risk
ROI reports what happened, or what a forecast says will happen. It does not report how likely other outcomes were.
Suppose two investments each returned 10% last year. One was a low-volatility holding whose value barely moved during the year. The other was a single speculative stock that dropped 35% before recovering. The ROI figures are identical, but the second investment exposed the money to a much wider range of results, including ones that never happened.
The US Securities and Exchange Commission's investor education site puts the general relationship simply: as investment risks rise, investors seek higher returns to compensate for taking those risks. That is why a high ROI on its own is not evidence of a good decision. It may simply be the reward for a risk that happened to go well.
Practical ways to keep risk in view:
- Compare an ROI against a benchmark of similar risk, not against the safest option available.
- Distinguish realized ROI (what actually happened) from projected ROI (a forecast), and never compare one directly with the other.
- For forecasts, work out a pessimistic, base and optimistic case rather than a single number.
Omitted Costs: The Denominator Problem
A small denominator makes a large ROI. Costs that commonly go missing include:
- Transaction costs: commissions, legal and closing fees, platform charges.
- Setup costs: installation, delivery, training, configuration.
- Running costs: maintenance, insurance, storage, subscriptions.
- Financing costs: interest on money borrowed to make the investment.
- Time: your own hours, if they would otherwise be paid or used elsewhere.
- Opportunity cost: what the same money could reasonably have earned instead. This is not a cash expense, but it is the right comparison point for deciding whether an ROI is worth having.
Worked example: an equipment purchase
A café buys a $12,000 espresso machine and expects it to add $6,000 a year in profit from extra sales.
The quick version: $6,000 ÷ $12,000 = 50% per year.
The fuller version (illustrative figures):
| Item | Amount |
|---|---|
| Machine | $12,000 |
| Installation and plumbing | $800 |
| Staff training time | $700 |
| Total upfront cost | $13,500 |
| Expected extra profit per year | $6,000 |
| Servicing and parts per year | −$900 |
| Interest on the equipment loan per year | −$600 |
| Net profit per year | $4,500 |
ROI per year = $4,500 ÷ $13,500 = 33.3%
Still a strong return, but a third lower than the first estimate, and the difference came entirely from costs that were real but easy to overlook. The payback period, the time to recover the upfront cost, is $13,500 ÷ $4,500 = 3 years. If the machine is likely to need replacing within that time, the investment looks very different again. For a closer look at when extra sales actually start covering costs, the Break-Even Calculator is a useful companion.
Marketing ROI: Revenue Is Not Profit
Marketing is where the gain-versus-profit confusion does the most damage.
A campaign costs $25,000 in ad spend, $5,000 in creative production and $2,000 in agency fees: $32,000 in total. It is credited with $72,000 in revenue. The business earns a 40% gross margin, so that revenue produces $28,800 in gross profit.
- Return on ad spend (ROAS) = revenue ÷ ad spend = $72,000 ÷ $25,000 = 2.88x
- Revenue over total campaign cost = $72,000 ÷ $32,000 = 2.25x
- Profit-based ROI = ($28,800 − $32,000) ÷ $32,000 = −10%
A campaign with a healthy-looking ROAS lost money once margin and the full campaign cost were included. ROAS is a legitimate efficiency measure for comparing ads, but it is a revenue ratio, not a return on investment.
One more caution: the $72,000 depends on how revenue was attributed to the campaign. If some of those customers would have bought anyway, the true return is lower still. The difference between these profit layers is covered in Gross Profit vs Net Profit.
Inflation: Nominal vs Real ROI
ROI is normally calculated in nominal terms, meaning the money amounts are not adjusted for changes in prices. A real return adjusts for inflation:
Real return = (1 + nominal return) ÷ (1 + inflation rate) − 1
A 7% nominal return in a year with 3% inflation gives:
1.07 ÷ 1.03 − 1 = 3.88% real return
The shortcut of subtracting inflation (7% − 3% = 4%) is close at low rates and drifts further off as rates rise. Over many years, the gap between nominal and real returns compounds. The Inflation Calculator shows how much purchasing power a sum loses over time, and How Inflation Reduces Purchasing Power explains why.
How to Interpret an ROI Figure
Before accepting any ROI number, whether your own or someone else's, ask:
- Over what period? If it is not stated, the figure cannot be compared with anything.
- Which costs are included? Look for fees, running costs, financing and time.
- Is the numerator profit or revenue? A revenue-based ratio can be positive while the investment loses money.
- Before or after tax? Both are valid, but mixing them is not.
- Realized or projected? Forecasts deserve a range, not a point.
- Compared with what? A 6% ROI is poor next to a similar-risk alternative earning 9% and good next to one earning 3%.
If an ROI figure survives all six questions, it is telling you something useful.
ROI vs Other Return Metrics
| Metric | What it measures | Best used for |
|---|---|---|
| Simple ROI | Total net profit as a percentage of cost | A quick read on one investment or projects of similar length |
| Annualized ROI / CAGR | Equivalent constant yearly rate | Comparing investments held for different periods |
| IRR | The rate that makes the present value of all cash flows zero | Projects with several cash flows at different times |
| NPV | Value today of future cash flows, minus the cost | Capital projects where the cost of money matters |
| Payback period | Time to recover the initial cost | Judging how long money is tied up |
| ROAS | Revenue per unit of ad spend | Comparing campaign efficiency, not profitability |
Simple ROI is the easiest to explain. IRR and NPV handle timing properly. Many decisions deserve at least two of these side by side.
Practical Scenarios
These are illustrative calculations, not benchmarks.
Property renovation. Purchase $300,000, renovation $50,000, closing and holding costs $15,000, sale at $410,000. Total cost $365,000, net profit $45,000, ROI 12.3%. If the project took nine months, annualized ROI is 1.123^(12 ÷ 9) − 1 ≈ 16.8%. If it took two years, it is about 6.0%. Same profit, very different use of capital.
Staff training. A company spends $8,000 on training, and sales attributed to the improvement add $35,000 in revenue the following year. If the gross margin on those sales is 30%, the extra profit is $10,500 and ROI is ($10,500 − $8,000) ÷ $8,000 = 31%. Calculated on revenue instead, it would appear to be 338%, which is the gain-versus-profit mistake again.
Software subscription. A team pays $12,000 a year for a tool that saves an estimated 200 hours at a fully loaded cost of $80 an hour, or $16,000. ROI is ($16,000 − $12,000) ÷ $12,000 = 33%, provided the saved hours are actually redeployed to useful work. If they are not, the saving is theoretical.
Common Mistakes
Using a gain instead of net profit. Price rise alone, or revenue alone, is not profit. Include income received and subtract every cost.
Ignoring the holding period. A total ROI without a time frame cannot be compared. Annualize before comparing.
Leaving costs out of the denominator. Fees, setup, running costs and financing all belong in it.
Treating ROI as a measure of risk. It is not. A high return may reflect high risk that happened to pay off.
Annualizing tiny periods. A strong month extrapolated to a year produces a number that is mathematically correct and practically meaningless.
Comparing projected ROI with realized ROI. A forecast has not faced reality yet.
Mixing nominal and real returns. Adjust both figures for inflation, or neither.
FAQ
What is a good ROI? There is no universal figure. A good ROI is one that beats a realistic alternative of similar risk over the same period, after all costs. Compare against that alternative rather than against a rule of thumb.
How do I calculate ROI for a multi-year investment? Calculate total ROI first, then annualize it: (1 + total ROI)^(1 ÷ years) − 1. If money was added or withdrawn during the period, use IRR instead.
What is the difference between ROI and ROAS? ROAS divides revenue by ad spend. ROI divides net profit by total cost. A campaign can have a strong ROAS and a negative ROI if margins are thin or other costs are large.
Is ROI the same as profit? No. Profit is an amount of money; ROI is that profit relative to what was spent. A $200 profit on $1,000 and a $200,000 profit on $1,000,000 are both 20% ROI.
How does inflation affect ROI? Standard ROI is nominal. To find the real return, divide (1 + nominal return) by (1 + inflation) and subtract 1. A 7% return with 3% inflation is about 3.9% in real terms.
Can ROI be negative? Yes. A negative ROI means the investment returned less than it cost. −50% means half the money spent was lost.
Does ROI account for risk? No. ROI measures a return, not the uncertainty around it. Compare investments of similar risk, or use risk-adjusted measures alongside ROI.
Related Tools
The ROI Calculator works out simple and annualized ROI from your cost and return figures. The CAGR Calculator gives the compound annual growth rate between two values. For projecting growth forward, use the Compound Interest Calculator. To check the margin behind a return, try the Margin Calculator, and to adjust for rising prices, the Inflation Calculator.
Related Articles
- Compound Interest Explained
- Common Financial Formulas
- What Is a Healthy Profit Margin?
- Gross Profit vs Net Profit
Sources
- Britannica Money, Return on Investment (ROI) - the ROI formula, the annualized ROI formula, and the points that basic ROI does not account for risk, volatility, fees or taxes.
- U.S. Securities and Exchange Commission, Investor.gov, What is Risk? - the principle that investors seek higher returns as investment risk rises.
- BDC (Business Development Bank of Canada), Return on investment (ROI) - ROI as profit relative to the cost of an investment, and its use alongside other profitability measures.
The worked examples in this article use illustrative figures. Every result was calculated directly from the formulas shown and rounded where stated.
Final Thoughts
ROI is popular because it turns a complicated decision into one readable percentage. That is also why it needs care. Get net profit right by counting every cost and every stream of income, state the period, annualize before comparing, and remember that the number says nothing about the risk taken to earn it.
Used that way, ROI is one of the clearest tools in any financial conversation. Used carelessly, it is one of the most convincing ways to be wrong.